Estate Planning After the 2026 Tax Reforms in India
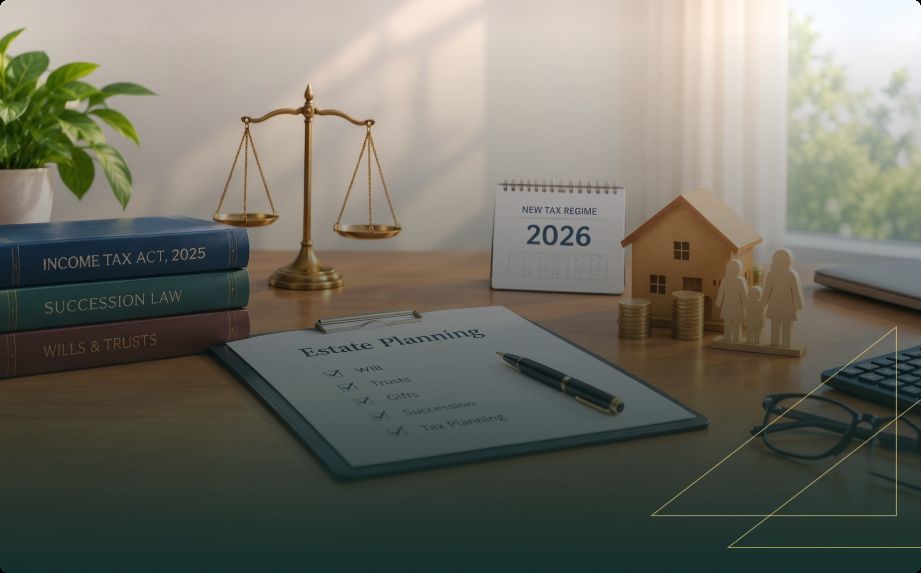
Learn how India's 2026 tax reforms affect estate planning, Wills, private family trusts, gifts, and wealth transfer. Discover what families should review.
Estate planning in India has entered a new phase.
With the Income-tax Act, 2025 that came into force on 1 April 2026 and significant changes to succession law, individuals and families should revisit their estate planning strategies to ensure they remain legally robust and tax-efficient.
While the reforms do not fundamentally change the way wealth is transferred on death, they have important implications for Wills, private trusts, gifts and estate administration.
More importantly, they reinforce the need to treat estate planning as an ongoing process rather than a one-time exercise.
The New Income-tax Act, 2025: What Has Changed? The Income-tax Act, 2025 replaces the Income-tax Act, 1961 with a modernised and simplified legislative framework.
Although many substantive tax principles continue under the new law, estate planning documents drafted under the previous regime should be reviewed to ensure that they remain current and effective.
One aspect that continues to provide certainty is that India has not reintroduced inheritance tax or estate duty.
Assets inherited through a Will or under the applicable succession laws are therefore not taxed merely because they pass to the legal heirs.
However, this should not be confused with complete tax exemption.
Once an inherited asset begins generating income, whether through rent, dividends, interest or a subsequent sale, that income will be taxable in accordance with the provisions of the Income-tax Act, 2025 .
Accordingly, tax planning should not end with the transfer of wealth; it should also consider the tax implications for the beneficiaries after they inherit the assets.
The Removal of Mandatory Probate.
An equally significant development is the removal of the mandatory probate requirement under Section 213 of the Indian Succession Act, 1925 .
Historically, probate was compulsory for certain classes of Wills executed within specified jurisdictions.
The removal of this requirement is expected to simplify estate administration and reduce both the time and cost involved in transferring assets to beneficiaries.
That said, probate has not become irrelevant.
In estates involving substantial assets, competing claims or the possibility of future disputes, obtaining probate may still provide greater legal certainty.
Financial institutions and other asset-holding entities may also continue to request probate in particular cases as part of their internal compliance procedures.
The practical implication is that probate is no longer a universal legal requirement, but rather a strategic decision based on the facts of each estate.
Existing Wills Should Be Reviewed.
Many people assume that a Will remains effective indefinitely once it has been executed.
While a validly executed Will continues to remain legally enforceable, it should be reviewed periodically to ensure that it accurately reflects the testator's current intentions and financial circumstances.
The 2026 legal changes provide an appropriate opportunity to review existing Wills, particularly where they contain references to the Income-tax Act, 1961 or where there have been significant changes in family circumstances or asset ownership.
A review should also consider whether the appointed executors, guardians and beneficiaries remain appropriate, and whether the Will adequately addresses newly acquired assets, digital assets and overseas investments.
Estate planning is most effective when it evolves alongside the family's financial and personal circumstances.
The Growing Importance of Private Family Trusts.
Private family trusts continue to play an increasingly important role in succession planning, particularly for families with substantial or complex asset portfolios.
Unlike a Will, which operates only upon the death of the testator, a trust allows assets to be managed and administered during the settlor's lifetime and after their demise in accordance with clearly defined objectives.
Trusts are particularly beneficial where there are family businesses, multiple immovable properties, vulnerable beneficiaries, minor children or beneficiaries residing outside India.
From a tax perspective, families should also review existing trust structures under the Income-tax Act, 2025 to ensure that the trust continues to achieve the intended tax and succession outcomes.
Related Guides & Articles
- Who Has Control Over Property Held in a Trust?
- Property Inheritance in India Explained
- You Built the Business. But Who Will Run It Next?
- A meaningful gathering at Hyatt Regency, Thrissur, on october 10, 2026
- How Can Families Prevent Important Assets From Being Lost Across Generations?
- Hindu Succession Act Explained: Who Inherits Property in India?
- Legal Heir Certificate in Kerala: Eligibility, Documents, Process & Uses
- Succession Planning: A Complete Guide for Families, Business Owners & NRIs in India